AWS Costs Kill Valuations: How a $287K AWS Bill Almost Killed a $50M Exit
Part I: The Champagne
The conference room smelled like victory and expensive cologne.
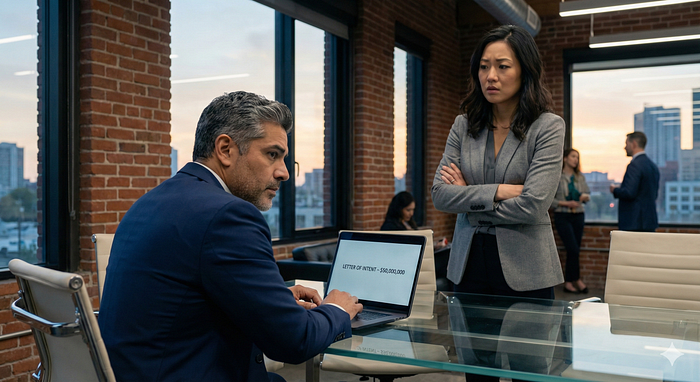
Glenn Torres, CEO of LogiScale, stared at the Letter of Intent on his laptop screen. $50 million. All cash. The acquirer, a publicly traded logistics giant, wanted his last-mile delivery optimization platform. Five years of 3 AM coding sessions, burned investor bridges, and maxed-out credit cards had finally paid off.
“We’re getting bought for ten times revenue,” Glenn said to his CFO, Rachel Kim. “Ten times.”

Rachel smiled, but her eyes didn’t. She’d seen the preliminary financials the acquirer requested. She knew what was coming.
“We still have to pass due diligence,” she said quietly.

Glenn waved her off. “We’re growing 240% year-over-year. They’re buying the growth story, not the spreadsheet.”
He was wrong.
Part II: The Audit
Three weeks into due diligence, Rachel’s phone rang at 11:47 PM.

It was Morris Blake, the acquirer’s VP of Corporate Development. No pleasantries. Just seven words that made her stomach drop:
“We need to talk about your AWS costs.”
The next morning, Rachel sat across from two tech auditors flown in from Boston. They had laptops, spreadsheets, and the dead-eyed stare of men who’d killed deals before.
The lead auditor, Jimmy, turned his screen toward her.

“Your AWS bill last month was $287,000. For a company doing $15 million in ARR, that’s… concerning.”
Rachel had known the AWS costs were high. What she hadn’t known was how catastrophic they looked under a microscope.
Jimmy clicked through the Cost Explorer dashboard like a coroner examining a body.
“Let’s start with EC2.”
LogiScale was running 247 EC2 instances. Of those, 89 were “zombie instances”: servers that had been spun up during load tests, proof-of-concepts, or forgotten experiments. They’d been idle for months. Still billing.
Monthly waste: $38,000.
“Now RDS.”
The engineering team had launched 14 separate RDS database instances, one for each client that demanded “dedicated infrastructure” during the sales process. None of them were using more than 12% of their provisioned capacity. They were paying for db.r5.8xlarge instances to serve what a db.t3.medium could handle.
Monthly waste: $52,000.
“And S3.”
LogiScale stored delivery route optimization data: millions of GPS coordinates, traffic patterns, historical shipping logs. All uncompressed. All in Standard tier storage instead of Glacier or Intelligent-Tiering.
Monthly waste: $24,000.
“And Data Transfer.”

This was the silent killer. LogiScale’s architecture had services in three different AWS regions (us-east-1, us-west-2, and eu-central-1) chattering constantly. Every API call between regions incurred a data transfer fee. Over a year, those pennies-per-gigabyte charges had metastasized into a six-figure line item.
Monthly waste: $41,000.
Jimmy closed his laptop.
“You’re burning $155,000 per month on infrastructure waste. Your total cloud COGS is running at $287K monthly. That’s $3.44 million annually, which is 23% of your revenue. Your Gross Margin is 62%. For a SaaS company at your stage, investors expect 75% or higher.”
Rachel felt the room tilt.
“What does that mean for the deal?”
Jimmy looked at Morris. Morris looked at Rachel.
“It means we’re repricing.”
Part III: The Math That Kills Deals
That night, Rachel sat alone in her office, staring at the same spreadsheet she’d shown Glenn a hundred times.

He’d never understood why Gross Margin mattered. To him, revenue was revenue. Growth was growth.
But acquirers don’t buy revenue. They buy Gross Profit .
Here’s the math that was killing them:
LogiScale’s Financials (Annual):
- Annual Recurring Revenue (ARR): $15,000,000
- Total Cost of Goods Sold (COGS): $5,700,000
- AWS Infrastructure: $3,440,000
- Support & Hosting: $1,460,000
- Other Direct Costs: $800,000
- Gross Profit: $9,300,000
- Gross Margin: 62%
The Acquirer’s SaaS Benchmark:
- Target Gross Margin: 75%
- Expected COGS at 75% margin: $3,750,000
- The Gap: $1,950,000 per year in excess costs
The acquirer’s valuation model was simple: they paid a multiple of Gross Profit, not revenue. And if they believed LogiScale’s unit economics were structurally broken, they’d assume the inefficiency would scale with growth.

That $1.95 million gap, compounded over five years at LogiScale’s growth rate, represented nearly $10 million in lost enterprise value.
Morris’s email arrived at 6:42 AM.
“Rachel: our revised offer is $40M. The AWS infrastructure represents structural inefficiency in your unit economics. If you can demonstrate a credible path to 72%+ Gross Margins within 60 days, we’ll reconsider. Otherwise, this is our final number.”
Rachel forwarded it to Glenn.
His reply was one word: “Fix it.”
Part IV: The Impossible Timeline
Rachel called an emergency meeting with the CTO, Nicole Chen.
“How fast can we optimize the infrastructure?”

Nicole pulled up a Jira board that looked like a war crime.
“To do this right? We’d need to:
- Audit and decommission every zombie EC2 instance.
- Rightsize all 14 RDS databases without causing downtime.
- Migrate S3 data to cost-optimized storage classes.
- Refactor the multi-region architecture to consolidate data transfer.
- Implement CloudWatch dashboards and auto-scaling policies to prevent future waste.”

She paused.
“That’s a six-month project. Minimum. And it’ll pull my entire team off product development.”
Rachel felt the walls closing in. They had three weeks until the deal deadline.
“What if we don’t fix it? What if we just… offset it?”
Nicole frowned. “Offset it how?”

“What if the AWS costs just… disappeared from our cash burn?”
“That’s not how accounting works, Rachel.”
“No,” Rachel said slowly. “But what if we could reduce the cash outflow enough that our Cloud COGS drops on the P&L?”
Nicole stared at her. “You’re talking about buying AWS credits.”
“I’m talking about buying heavily discounted AWS credits and using them to cover our burn until the deal closes.”
“That’s financial engineering.”
“That’s my job.”
Part V: The Discovery
Rachel had heard whispers about Credex at a CFO roundtable three months earlier. A marketplace for unused cloud credits. She’d filed it away as “too niche to matter.”
Now, it was her only play.
She opened credex.rocks.

The pitch was simple: Startups that shut down, pivot, or get acquired often have unused AWS credits from investor programs, accelerators, and AWS Activate grants. Credex buys these credits and resells them to companies that need them.
She clicked “Browse Listings.”
The inventory was live:
- $25,000 in AWS credits. Valid for 2 years. 45% off: $13,750.
- $100,000 in AWS credits. Valid for 22 months. 42% off: $58,000.
- $250,000 in AWS credits. Valid for 24 months. 43% off: $142,500.
- $350,000 in AWS credits. Valid for 21 months. 44% off: $196,000.
Rachel did the math.
LogiScale was burning $287K monthly on AWS. Over the next 12 months, that’s $3.44 million in cash outflow.

If she bought $1 million in AWS credits at an average 43% discount, LogiScale would pay approximately $570,000 upfront. Those credits would cover nearly 3.5 months of their AWS burn.
But here’s the key: for financial reporting purposes , that $570K cash payment gets recognized as Cloud COGS over the credit usage period. Meanwhile, the actual AWS bills get paid down using the credits instead of cash.
The margin transformation on the P&L:
Get Credex’s stories in your inbox
Join Medium for free to get updates from this writer.
Remember me for faster sign in
Current Quarterly Financials:
- Quarterly Revenue: $3,750,000
- Quarterly AWS Cash Spend: $861,000
- Other COGS: $565,000
- Total COGS: $1,426,000
- Gross Margin: 62%
After Credex Credits (Next Quarter):
- Quarterly Revenue: $3,750,000
- Quarterly AWS Expense (using credits bought at discount): $490,000
- Other COGS: $565,000
- Total COGS: $1,055,000
- Gross Margin: 72%
The credits didn’t fix the underlying infrastructure waste. But they reduced the cash impact enough to push margins into acceptable territory for the 90-day window that mattered.
Part VI: The Verification
Rachel scheduled a call with Credex’s senior engeering leader, an ex-AWS solutions architect named Elena Wright.

“I need roughly $1 million in AWS credits. I need them verified. I need full ownership transfer. And I need this done in one week.”
Elena didn’t blink.
“We don’t have a single seller with that amount. AWS Activate programs cap at $100K to $350K per company. But we have multiple sellers right now. Let me walk you through what’s available.”
She pulled up her inventory.
“Package 1 : $100,000 in credits from a Y Combinator batch company that shut down. They received AWS Activate credits through YC’s founder program. Valid for 24 months. 45% off: you pay $55,000.
Package 2 : $250,000 from a Techstars-backed logistics startup that migrated to Azure. Credits from their Techstars AWS Activate package. Valid for 22 months. 43% off: you pay $142,500.
Package 3 : $300,000 from a Sequoia portfolio company that pivoted to B2B and moved to GCP. Credits from Sequoia’s portfolio program with AWS. Valid for 23 months. 42% off: you pay $174,000.
Package 4 : $350,000 from an Andreessen Horowitz-backed fintech. They received maximum-tier AWS Activate credits and no longer need them after an acquisition. Valid for 21 months. 44% off: you pay $196,000.
Total: $1,000,000 in credits for $567,500. Average discount: 43%.”
Rachel did the mental math. Four separate account transfers. But it solved the problem.
“What’s the risk?” Rachel asked.

“Minimal. These are all legitimate AWS Activate credits granted through recognized accelerator and VC programs. We verify every credit balance with account screenshots and API checks before listing. You’ll sign a mutual NDA with each seller through us. Their identities stay confidential. Each account ownership transfers to your designated emails. You get root admin access, change passwords, set up 2FA. They become your accounts.”
“Four separate accounts?” Rachel asked.
“Yes, but you can consolidate them under your AWS Organizations billing. All four accounts roll up to a single payer account. AWS treats it as one consolidated bill, and the credits apply automatically across your organization.”
Rachel leaned forward. “Timeline?”
“We start paperwork tomorrow. NDA signatures, account screenshots for verification, invoice details. Once you confirm payment release date, we complete all four transfers within one week. You’ll have full control of all accounts and can start using credits immediately.”
Rachel exhaled. “Send the NDAs and account screenshots for all four packages.”
Part VII: The Second Audit
Two weeks later, Rachel sat across from Jimmy and Morris again.

She slid three documents across the table:
“We’ve implemented an AWS cost strategy. Our Cloud COGS dropped by 43% on a cash basis. Here’s the proof.”
Jimmy frowned. “Your Cost Explorer still shows the same usage patterns. The $287K monthly burn is still there. How did costs drop?”
“We acquired $1 million in verified AWS credits at an average 43% discount from four different sources. All AWS Activate credits from recognized accelerator and VC programs: Y Combinator, Techstars, Sequoia, and Andreessen Horowitz portfolio companies. The credits are now in our owned accounts with 21 to 24 months validity. Our cash outflow for AWS dropped from $861K quarterly to approximately $490K, which is what hits our COGS line.”
Morris leaned forward. “You’re using marketplace credits? What happens when they run out?”
“These aren’t marketplace credits,” Rachel corrected. “These are AWS Activate credits that were granted to venture-backed companies through their official investor and accelerator programs. Fully legitimate. Full ownership transferred to us through proper account transfers. No different than if we’d received them directly from our own investors.”
She pulled up her laptop and showed the account transfer documentation, credit balances across four accounts, and the validity periods.
“We’ve consolidated all four accounts under our AWS Organizations structure. They function as a single billing entity. By the time these credits exhaust in 21 to 24 months, we’ll either be part of your AWS Enterprise Agreement, or we’ll have completed the infrastructure optimization. This gives us the financial runway to close the deal without tanking our unit economics on paper.”

Jimmy studied the P&L statement.
The numbers were there. Gross Margin: 72%.
“What about the underlying infrastructure waste?”
“That’s a separate workstream,” Rachel said. “Nicole’s team has a 6-month optimization roadmap. But that’s an operational improvement , not a financial blocker . The credits solved the cash problem. The optimization will solve the efficiency problem. And frankly, once we’re under your umbrella, your infrastructure team will probably have better solutions than we could implement in three weeks anyway.”
Morris and Jimmy exchanged a look.
Jimmy closed the folder.
“Your Gross Margin is now 72%. That’s acceptable. The operational improvements can happen post-acquisition.”
Part VIII: The Close
Six weeks later, Glenn and Rachel stood in a law office in Palo Alto, signing the final acquisition documents.

$50 million. All cash.
As they walked out, Glenn turned to Rachel.
“I still don’t fully understand what you did.”
Rachel smiled.
“I bought time. Credex gave us $1 million in AWS credits for $567,500. That $432,500 in savings, spread over the credit usage period, was enough to transform our Cloud COGS from a liability into a manageable line item. Our Gross Margin went from ‘red flag’ to ‘acceptable.’”
“So we didn’t actually fix the infrastructure?”
“Not yet. But we fixed the cash burn . And in M&A, cash burn is what kills valuations. The acquirer doesn’t care if you’re running zombie EC2 instances. They care if those instances are bleeding cash that destroys your margins.”

Glenn laughed. “You’re terrifying.”
“I’m a CFO,” Rachel said. “It’s my job to make the numbers work.”
The Lesson: Why AWS Costs Kill Valuations (And How to Fight Back)
If you’re a founder preparing for an exit, here’s what you need to know:
1. Acquirers Value Gross Profit, Not Revenue
A SaaS company with $15M in ARR and 62% Gross Margins is worth less than a company with $12M in ARR and 78% Margins. Why? Because the second company has better unit economics. Excess cloud costs destroy that quality.
2. Tech Due Diligence Focuses on Cash COGS
Auditors will examine your P&L to understand your Cost of Goods Sold. Cloud infrastructure is typically 40–60% of total COGS for SaaS companies. If your AWS bills are eating 23% of revenue when they should be 12–15%, that’s a valuation weapon.
3. You Can’t Fix Infrastructure Overnight
Rightsizing EC2, migrating S3 storage classes, and refactoring multi-region architectures takes months. If you’re three weeks from closing, code rewrites aren’t an option.

4. Financial Engineering Can Bridge the Gap
Buying discounted AWS credits doesn’t fix the underlying inefficiency, but it reduces cash outflow enough to improve your Gross Margin on paper. For a 90-day window during due diligence, that’s enough to save a deal.
5. The Credits Are Legitimate and Low-Risk
Platforms like Credex source credits from:
- Startups that received AWS Activate grants from VCs and accelerators (Y Combinator, Techstars, Sequoia, a16z, etc.)
- Companies that pivoted to other cloud platforms (GCP, Azure)
- Startups that shut down with unused credits
The credits are valid for up to 2 years, transfer with full account ownership, and come with verification and replacement guarantees.
6. How the Math Actually Works
Here’s the real impact on a $15M ARR company burning $287K monthly on AWS:
Without Credex:
- Monthly AWS bill: $287,000
- Paid in cash: $287,000
- Quarterly Cloud COGS: $861,000
- Annual Cloud COGS: $3,440,000
- Gross Margin: 62%
With Credex:
- Buy $1M credits for $567,500 (43% discount)
- Credits cover ~3.5 months of usage
- Effective cost during credit period: ~$163,000/month
- Quarterly Cloud COGS (blended): ~$490,000
- Annual savings: ~$1,490,000
- Gross Margin: 72%
That 10-point margin improvement is the difference between a $50M exit and a $40M exit.
The $10 Million Question
Would you rather:
- Spend six months rewriting infrastructure and risk losing your deal window?
- Or spend $567,500 on discounted credits and close at your original valuation?
Rachel chose the second option.
The deal closed.
LogiScale is now part of a publicly traded company.
And Rachel? She’s advising three other startups on how to survive Tech Due Diligence.
Her first recommendation: Check your Cloud COGS. Then check Credex.
Because in M&A, a $287K monthly AWS burn isn’t just a cost problem.
It’s a $10 million valuation haircut waiting to happen.
About Credex: Credex is a marketplace for verified, unused cloud credits from AWS, GCP, and AI platforms like OpenAI and Anthropic. Credits are sourced from startups with unused AWS Activate grants (from accelerators like Y Combinator, Techstars, and VC programs), companies that pivoted platforms, or portfolio companies with excess credits. All credits come with mutual NDAs, full ownership transfer via account transfer, and a replacement guarantee if credits become inaccessible. Typical discounts: 40–45% off face value. Validity: up to 2 years for AWS credits. Delivery timeline: within 1 week after paperwork completion.
Follow us on LinkedIn
This story is based on the real journey of a Credex client founder, though the founder’s name and company name (LogiScale) have been changed to protect their privacy. The challenges, economics, and solutions described are drawn from authentic experiences navigating AI infrastructure cost optimization in 2024–2025.
Credex represents an emerging category in AI infrastructure: verified marketplaces for discounted LLM credits with full ownership transfer, enterprise rate limits, NDA protection, and refund guarantees. For founders exploring LLM cost optimization or buying AWS credits at a discount, the question isn’t whether these solutions exist, it’s whether you’ll discover them before your runway runs out.